ARIA · loading
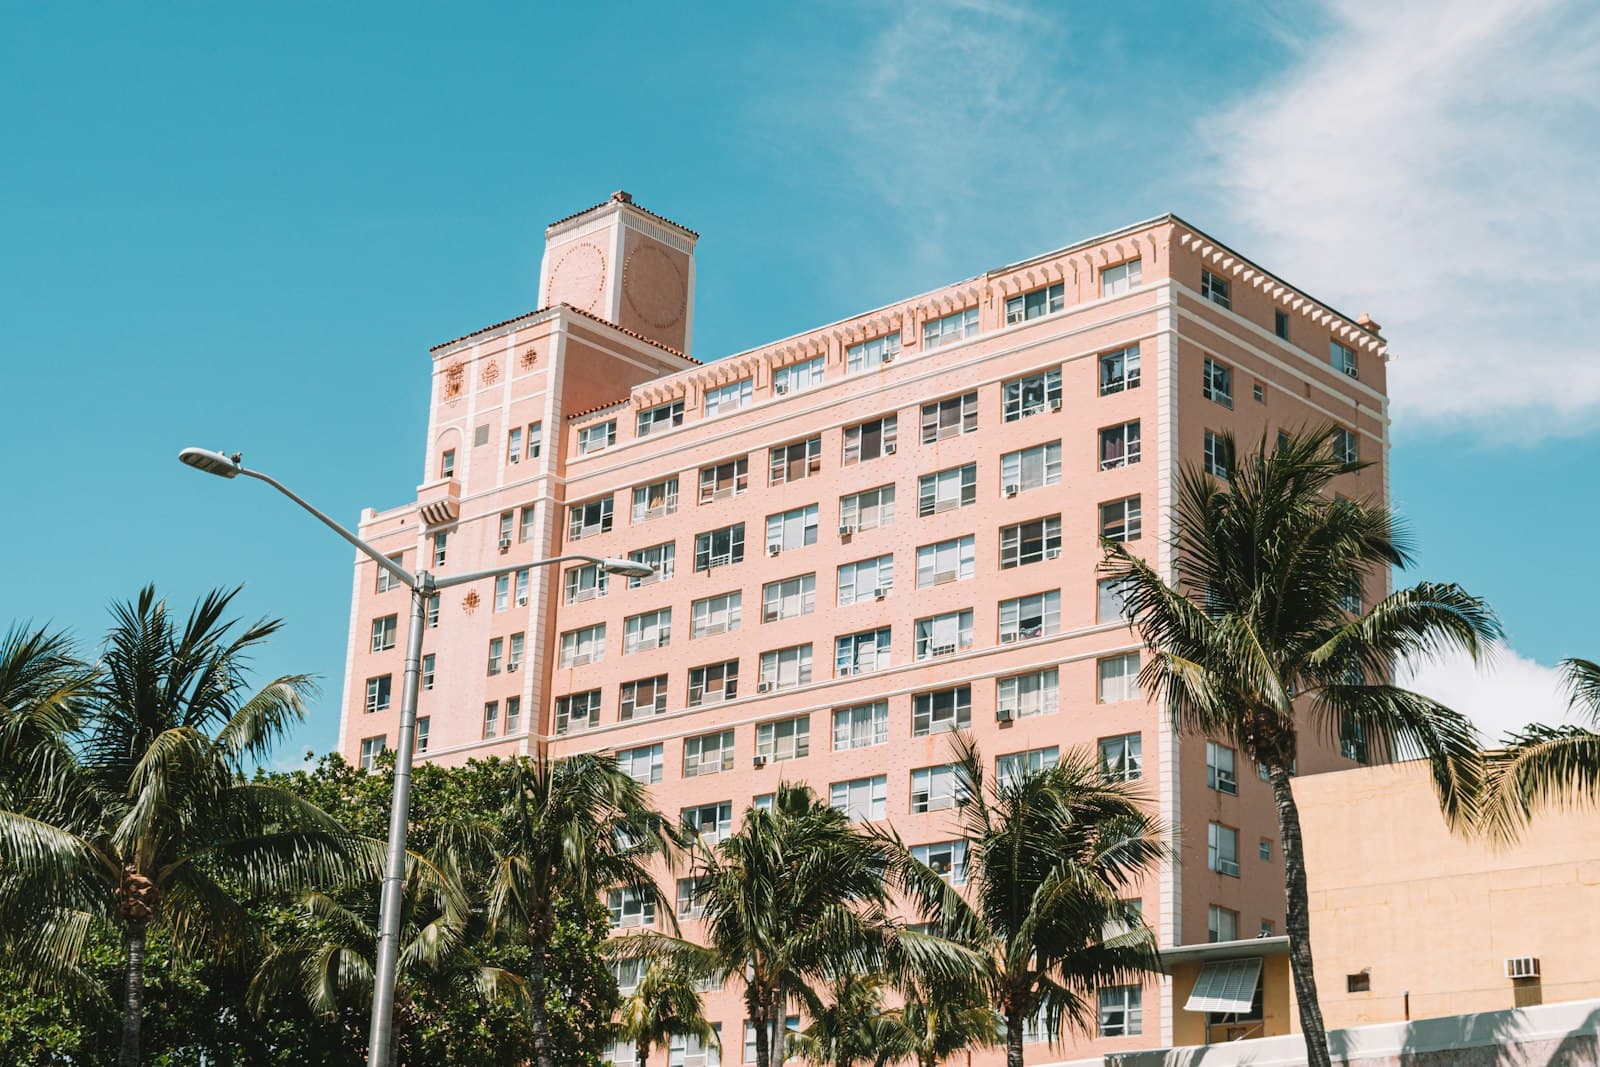
Real estate carries the largest property-loss tail of any industry. A single weather event can exhaust a year of EBITDA. Beyond the building itself, every tenant relationship, every rental application, every common-area incident creates liability exposure. The line that surprises owners is fair-housing / discrimination claims. They're routinely underinsured.
Drawn from analysis of mid-market accounts in this class. The structural ones, what's missing from the coverage rather than what it costs, are the ones that end up on a balance sheet.
The lines ARIA recommends for a well-structured coverage stack in this industry, in the order they typically attach.
ARIA can now evaluate the controls, dependencies, and operating risks that shape how your business responds before, during, and after a loss. About 3 minutes. A Business Preparedness Score, public website security signals, and the three actions that matter first.
A Category-3 hurricane makes landfall, causing wind, storm-surge, and subsequent water damage to a 240-unit garden apartment complex. Direct damage estimated $14M; loss-of-rents during 9-month rebuild estimated $3.8M.
Standard property carrier responds with $8M limit, but wind sublimit caps at $5M for named-storm losses. NFIP pays $500K. Owner absorbs $8.7M direct + $3.8M business interruption out-of-pocket. Refinancing breaks the loan covenants; bank forecloses.
RiskMind structures: $15M blanket property + carved-out $10M dedicated wind layer (Lloyd's of London) + $5M private excess flood. Loss-of-rents extension period set to 18 months. Total claim payout: $17.4M of $17.8M loss. Owner refinances at new value, retains the asset. Indicative annual premium for the upgraded coverage: $420K–$520K.
Illustrative scenario · how this claim pattern breaks, not a client history
Annual premium distribution across the full coverage stack for a comparable business in your industry. ARIA refines your exact position once it reads your declarations page.
Illustrative ranges for this class · replaced by cited findings when ARIA reads your policies
In market at 120 days, terms at 60, bound at 30. Select the month and those dates are yours, not a generic example. No email, no form.
Ninety days before it, you get one market read for your industry, from me. Nothing else happens without you.
ARIA pre-loads your real estate & property mgmt exposure profile the moment you click. Peer benchmarks, top risks, and the carriers in appetite at your scale.
In writing, within 48 hours, free. If the read shows your current program is right, I will tell you to stay put, in writing. You lose nothing either way.
Nothing binds until a licensed Risk Strategist signs the placement
ARIA · live across every page